© Copyright Acquisition International 2026 - All Rights Reserved.

Article Image - Considerations When Securing a Loan Against Your Property
Posted 15th October 2020

Considerations When Securing a Loan Against Your Property

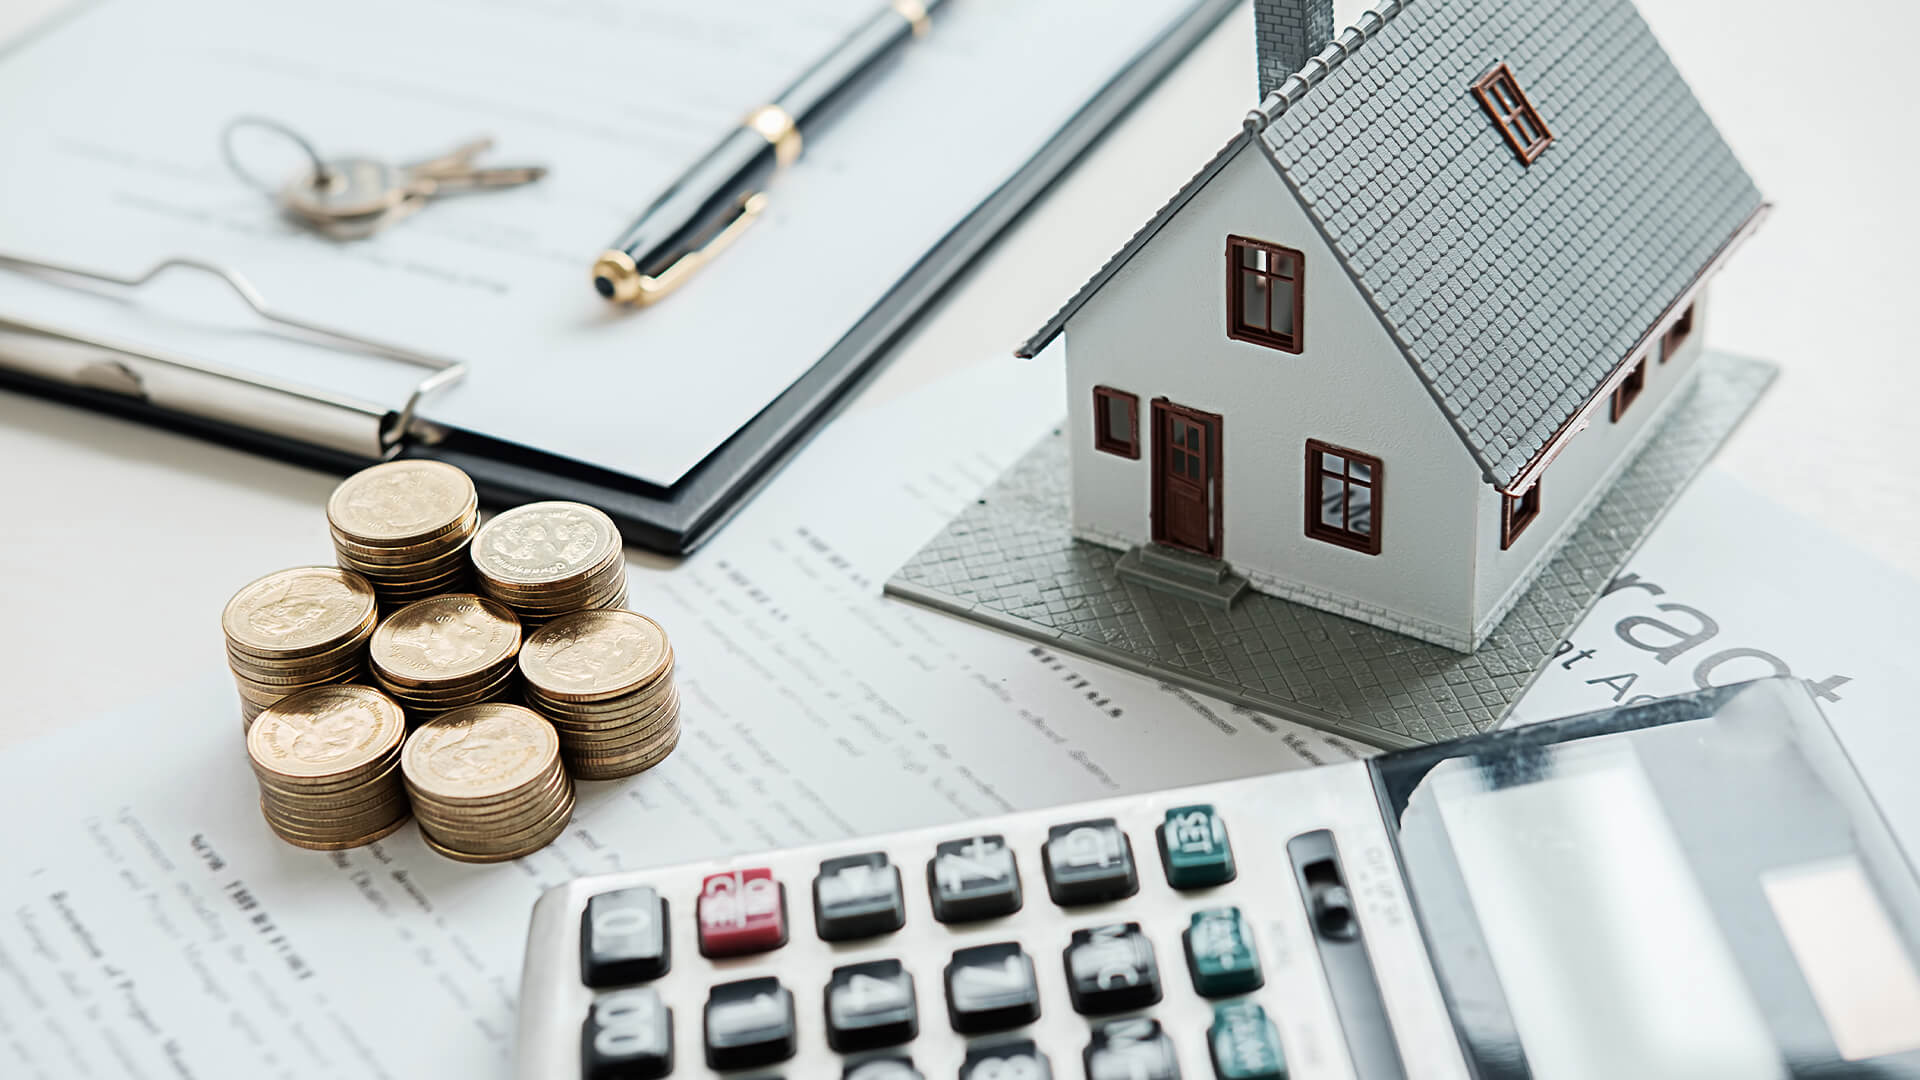
Securing a loan against your property for any reason comes with a degree of risk by its very nature. Some loans such as mortgages will of course need to be secured against a property, whereas in other cases, you may not need to secure the loan against bricks and mortar if at all. One of the key benefits of securing loans in this way is that from the borrower’s perspective, more money can be borrowed so long as there is enough equity owned by the borrower in the property.

Mouse Scroll AnimationScroll to keep reading

Let us help promote your business to a wider following.

Considerations When Securing a Loan Against Your Property

house loan

Securing a loan against your property for any reason comes with a degree of risk by its very nature. Some loans such as mortgages will of course need to be secured against a property, whereas in other cases, you may not need to secure the loan against bricks and mortar if at all.

One of the key benefits of securing loans in this way is that from the borrower’s perspective, more money can be borrowed so long as there is enough equity owned by the borrower in the property. For example, in the case of loans for home improvements and refurbishments, the borrower will need to own enough equity in the property to satisfy the underwriters as part of the due diligence run by lenders.


Why Do Lenders Require a Property For the Loan?

From a lender’s perspective the risk is hugely reduced with property loans as the very property the loan is often to be used upon acts as a form of collateral on the loan. This means that should the borrower default on the loan and fail to make their required repayments, the borrower can undertake court proceedings to seize the property to recoup their losses.

There are numerous reasons why people utilise loans that are secured to their property. It is not just about risk, but also about the amount of money that can be borrowed as well as some loans and financial arrangements requiring a property or other high value asset as part of the arrangement between the borrower and the lender.


What Types of Loans Require Properties as Security?

Typically, it is mortgages of any nature which require a property against which they must be secured. Both first charge and second charge mortgages will require a property so that the lender can be satisfied that the money they lend; usually many tens or hundreds of thousands of pounds is provided with as little risk as possible.

First Charge Mortgages – These mortgages are those which most people will be most familiar with and these mortgages are the most commonly utilised form of secured finance in the UK if not the world. The basic premise is familiar whereby a percentage of the value of the property is borrowed by the owner and that amount is then secured against the property with repayments plus interest made over anywhere from a handful of years to a few decades.

Second Charge Mortgages – These, as their name suggests are mortgages which are taken out in addition to a regular first charge mortgage. They require the agreement and consent of both the first and second charge lenders. However, if a borrower owns enough equity in a property and is already paying off their first charge mortgage, so long as certain criteria are met, they can take out a second charge loan on the property. However, these loans do tend to come with additional charges and higher interest which is worth bearing in mind before applying for the finance.


Using Property Loans for Business Purposes

It is possible to use loans which are secured against a property for business investment purposes and this is something which some business owners may prefer compared to utilising investors.

For example, there are many venture capitalists (VCs) in the UK and many of the top UK VCs are very willing to lend to businesses and startups. However, as an investor-business relationship, the business will need to give up some degree of control in the form of shares and equity, something that may not be right for every business.

Therefore, some business owners may well turn to loans secured against a property they own. It is usually recommended not to secure a loan of this nature against your primary residence and place of abode; your home. The reason for this being that no matter what happens, if your home property is separate from your business you will always have a roof over your head.

You should always manage and consider the risks involved when it comes to securing a loan against a property as there is always the risk of having the property repossessed should you forfeit the loan and fail to make repayments. If you do end up having your property taken as a result of failure to repay loans you will also find it incredibly difficult to secure any future credit for your business.
Categories: Finance


You Might Also Like
Read Full PostRead - Eye Icon
Challenges and  Alternatives for the  Brazilian Importer
Finance
27/05/2015Challenges and Alternatives for the Brazilian Importer

We hear from Carlos Ayub as he talks us through the challenges and alternatives for the Brazilian importer under the transfer pricing regulations.

Read Full PostRead - Eye Icon
FCA Publishes Interim Feedback on Review of the Rules for Crowdfunding
Finance
09/12/2016FCA Publishes Interim Feedback on Review of the Rules for Crowdfunding

On 9th December, the Financial Conduct Authority (FCA) gave an update on the post-implementation review of the loan-based and investment-based crowdfunding market. Their earlier call for input raised a number of issues for discussion; the feedback statement pr

Read Full PostRead - Eye Icon
A Long and Strong Presence
Innovation
11/09/2017A Long and Strong Presence

A Long and Strong Presence

Read Full PostRead - Eye Icon
4 Tips for Hiring Supervisors for Your Organisation
Legal
30/08/20244 Tips for Hiring Supervisors for Your Organisation

Any business in any industry will arrive at a point when it needs the help of skilled supervisors who can focus on specific aspects of the organisation. Nothing good ever comes out of stretching yourself too thin, so it’s important to look for people who can

Read Full PostRead - Eye Icon
How Can Sales Teams Improve Their Negotiation and Closing Skills?
News
08/01/2026How Can Sales Teams Improve Their Negotiation and Closing Skills?

In today’s competitive marketplace, sales effectiveness is anchored in two core capabilities — negotiation and closing.

Read Full PostRead - Eye Icon
Key Player in the Philippine Legal Industry
Legal
20/03/2019Key Player in the Philippine Legal Industry

MOSVELDTT Law Offices is full-service firm grounded on legal competence and distinguished by their uncompromising work ethic. Recently, the firm found success in AI’s Global Excellence Awards 2019. On the back of their win, we profiled the firm and spoke to

Read Full PostRead - Eye Icon
Indonesia’s Most Credible Intellectual Property Firm
Strategy
05/12/2016Indonesia’s Most Credible Intellectual Property Firm

Am Badar & Partners is one of the leading Intellectual Property Firms in Indonesia that handles all areas of IP and related IP matters.

Read Full PostRead - Eye Icon
Most Innovative Law Firm of 2016, Glasgow
Legal
04/04/2016Most Innovative Law Firm of 2016, Glasgow

The Most Innovative Law Firm of 2016, Glasgow was awarded to EmployEasily Legal Services

Read Full PostRead - Eye Icon
Preserving a Heritage of Excellence
Innovation
23/05/2018Preserving a Heritage of Excellence

Proserv is a global leader with a worldwide presence, offering a fresh alternative in the delivery of engineering and technical services to the energy, process and utility markets.


Our Trusted Brands

Acquisition International is a flagship brand of AI Global Media. AI Global Media is a B2B enterprise and are committed to creating engaging content allowing businesses to market their services to a larger global audience. We have a number of unique brands, each of which serves a specific industry or region. Each brand covers the latest news in its sector and publishes a digital magazine and newsletter which is read by a global audience.

Arrow