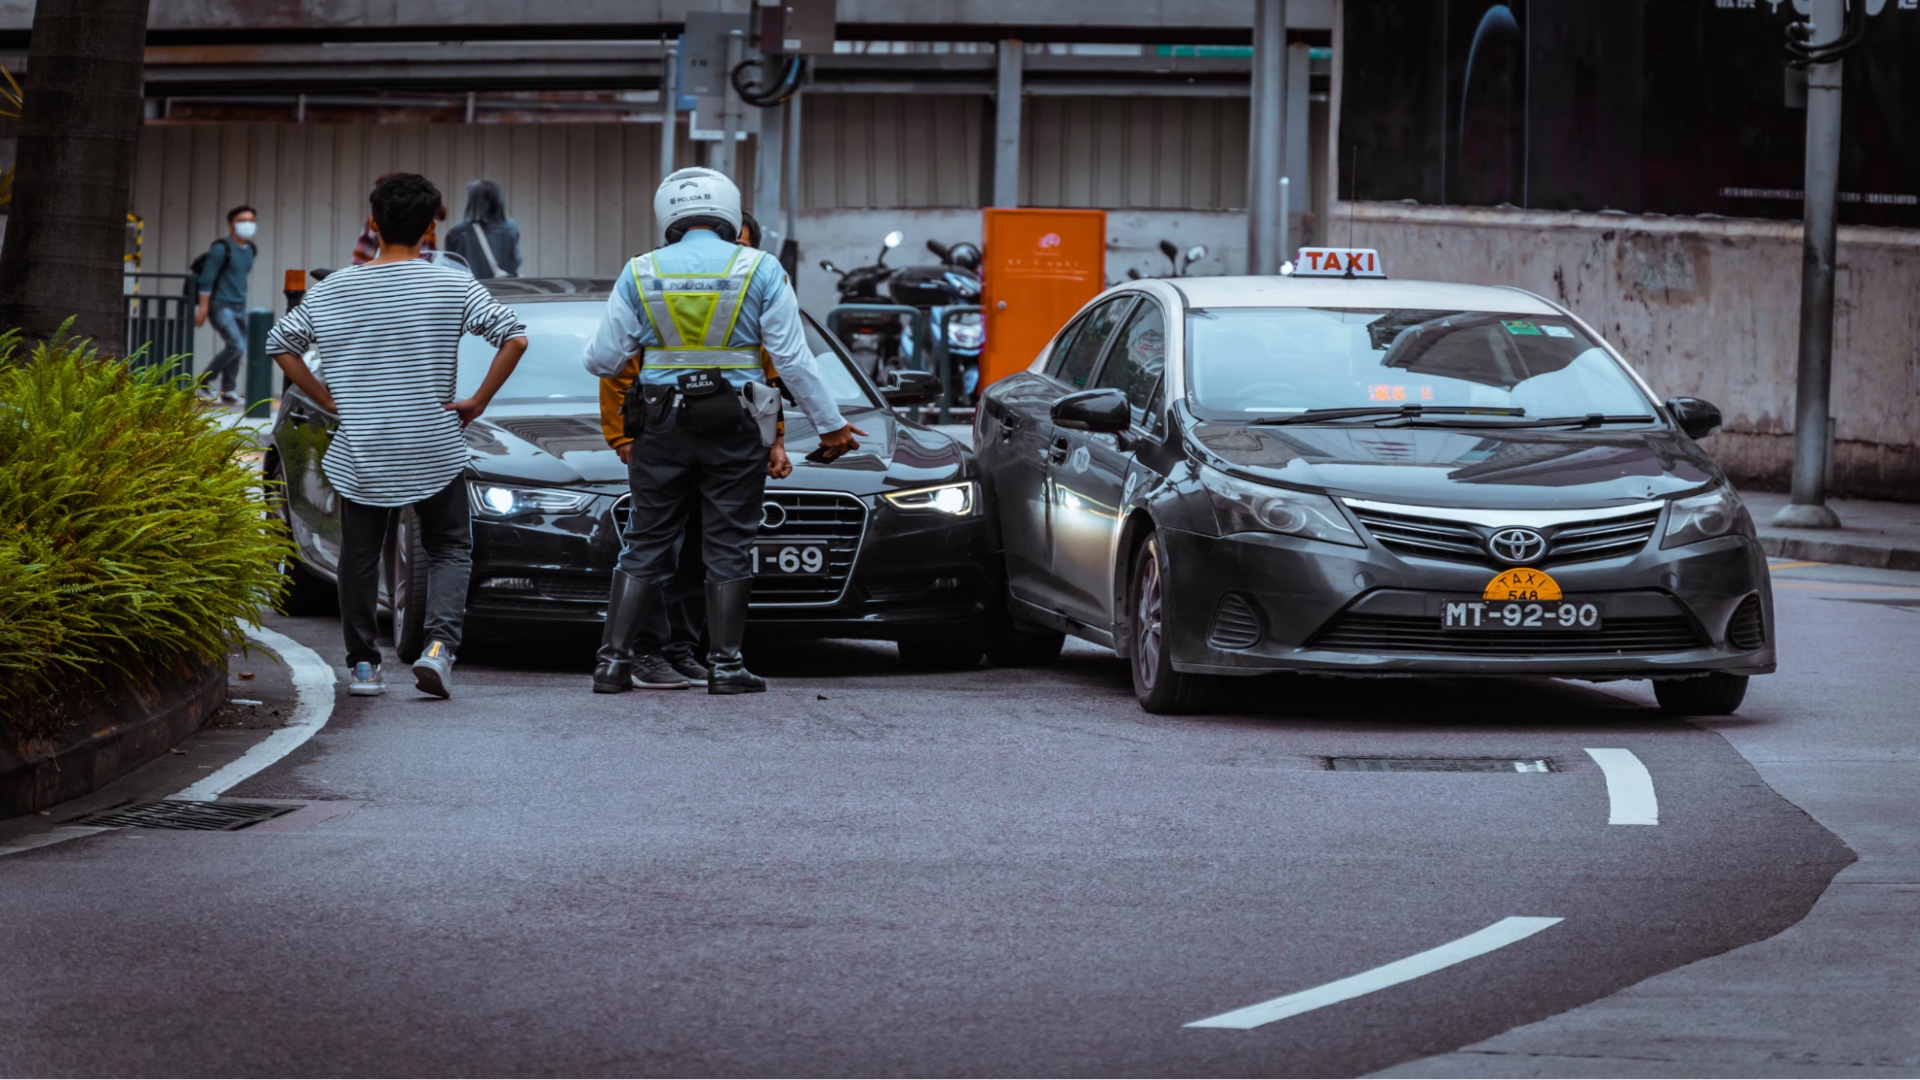

Consider a hypothetical Texas electrician who is rear-ended on a Tuesday. By Thursday, she has a shoulder-related work restriction from her doctor and a client email asking why a panel upgrade hasn’t happened. Her lease, truck payment, and supplier invoices still arrive on schedule.
If you’re self-employed, especially an owner-operator in Texas, you may have no HR department to print a wage statement. Records of your earnings and work interruptions are spread across your books, calendar, and medical file. Documenting a loss means bringing those records together.
This article provides general information. The treatment of a claim depends on the facts, coverage, and applicable rules.
Build Your Pre-Accident Income Baseline
Start with records you already have. The IRS identifies sales slips, invoices, receipts, deposit slips, and canceled checks as supporting business documents. These records supply the information entered in your books. Gather your tax returns with the relevant business schedules, monthly profit-and-loss statements, invoices, business bank statements, client contracts, and payment-platform statements.
Make each spreadsheet entry traceable to its source documents. These records establish the financial history; you’ll also need to explain how the injury interrupted your work.
Separate sales from your earnings. IRS Publication 334 describes net profit as business income minus business expenses. How you pay yourself matters too. Salary, owner draws, distributions, and retained profit serve different purposes. A drop in one does not automatically establish a personal loss of the same amount. Personal earning loss is a separate question from business receipts or profit. Ask your accountant to explain how you were compensated before the crash.
Choose a fair comparison period. Compare the affected months with periods that resemble them. If spring is always your busiest stretch, a slow July provides little context on its own. Flag one-off contracts, price changes, or supplier problems that would have affected earnings anyway. Explain why you chose the comparison period, and ask the person reviewing your claim whether additional records are needed.
Connect Each Missed Job to Your Recovery
A useful way to document lost income after a car accident is to pair documented work limitations with specific jobs you couldn’t complete.
Record work restrictions. Ask your doctor to document any work limitations that apply, such as lifting limits, driving restrictions, or reduced hours, and their expected duration. A spreadsheet alone cannot establish the medical reason for missed work.
Match each interruption to a job. Keep a dated work-impact log. For each entry, identify the job or appointment, the restriction that affected it, the client message, the related invoice or quote, and what eventually happened to the work. Save cancellation emails, accepted bookings, calendar screenshots, and timesheets showing reduced hours.
An organized log gives counsel a concrete account of the work interruption to review alongside financial and medical records. For a Fort Worth crash, Stogner Trial Law handles car accident claims that include lost wages and diminished earning capacity, and offers a free consultation. Review any representation agreement for its fee terms and how case expenses are handled.
Separate delays from losses. Distinguish confirmed bookings from prospective work, and delayed payments from jobs that never happened. Mark each entry as canceled, postponed, completed late, or reassigned. If you paid a subcontractor to cover a job, record that cost separately so the same financial effect isn’t counted twice.
| What you are showing | Supporting records |
| Normal earnings | Tax schedules, profit-and-loss statements, bank deposits |
| Work limitations | Doctor’s notes stating restrictions and duration |
| Specific missed work | Work-impact log, cancellation emails, contracts, calendar |
Prepare a Clear Loss Summary
Make the calculation traceable. A one-page summary should identify the affected period, your baseline method, the expected earnings that method supports, actual earnings for the period, and a source reference for every figure. Show avoided costs, replacement-labor expenses, and work you later completed on separate lines. Tax records help establish your earnings pattern, while the amount claimed requires a separate assessment. Keep projections of future missed work in a labeled section apart from documented past interruptions. A clear explanation of lost earnings versus earning capacity can help distinguish the two.
Account for unrelated changes. A fall in revenue alone does not establish that the crash caused it. Note seasonal demand, delayed payments, price changes, customer cancellations unrelated to the injury, and work you could still perform. Keep a short explanation and supporting record for each major variance so the summary does not treat every lower deposit as an accident-related loss.
Get the right review. An accountant can check that your summary agrees with the underlying records and explain your compensation structure. A legal professional can assess which losses may be claimable and which insurance coverage might apply.
For Texas readers, the Texas Department of Insurance explains that Texas auto policies include personal injury protection unless it is rejected in writing. Check whether you retained that coverage and what limits apply; its availability does not mean it will pay the entire claimed loss. This Texas-specific information should not be assumed to apply nationwide. Rules elsewhere differ: a look at employee injury costs in Florida notes that PIP there can provide certain income-related benefits in qualifying motor vehicle injury cases, and keeps those benefits separate from an injured person’s claim and the employer’s operating costs.
Before sharing the summary, reconcile each line to a record number, identify missing documents, and list questions for the accountant or legal professional reviewing it. Keep documented past losses separate from estimates of future effects, and identify any assumptions used in the comparison period.
Preserve the source packet. Keep original statements, invoices, medical notes, and messages in a dated folder, while using a copy for annotations. Number the supporting records and avoid changing the underlying files after the summary is prepared. If a figure changes, save the revision and note why.
For a review with counsel, prepare an indexed summary, the original records behind it, and a dated list of unanswered questions.
Conclusion
For a Texas owner-operator, a useful income record is organized, supported, and honest about uncertainty. Preserve the financial history, connect each affected job to documented limitations, separate delayed work and replacement costs, and ask qualified accounting and legal professionals to review the summary. These steps make the financial story easier to evaluate without guaranteeing a particular claim result.
FAQs
What if I don’t have pay stubs?
Use invoices, tax returns with business schedules, client contracts, and business bank records to document your earnings history. Pair those records with medical restrictions and evidence of specific work interruptions.
How should I handle seasonal earnings?
Compare the affected months with comparable periods, such as the same months in earlier years. Explain unusual swings and why the chosen period represents your normal earnings.
What if a job was postponed rather than canceled?
Record when it was eventually completed and paid. Note any shortfall, such as a reduced scope, for review rather than recording the full original value as lost.
Can I include income I may miss in the future?
Keep projections in a separate, labeled section and have an accountant and a legal professional assess them. Show the assumptions and supporting records separately from documented past interruptions.