
General liability coverage is required for everyone. If you own a small business, it’s your livelihood and should be well protected. You must purchase beyond required workers’ compensation and general liability to ensure that you are fully protected against all possibilities. Let’s look at some statistics to determine which commercial policies are important.
General Liability Insurance
This should be your first move when it comes to insurance if you run a company. It protects you against a variety of claims, including bodily harm, property damage, and personal injury. Business owners and directors’ policies (BDPs) typically include both property and liability coverage, as well as general liability insurance.
Workers’ Compensation Insurance
A workers’ compensation insurance policy, like general liability insurance, is usually required by law when running a company. A workers’ compensation insurance covers medical expenditures, a portion of missed pay, rehabilitation, and death benefits in the event an employee gets injured or sick at work.
Riders For Auto and Home Insurance
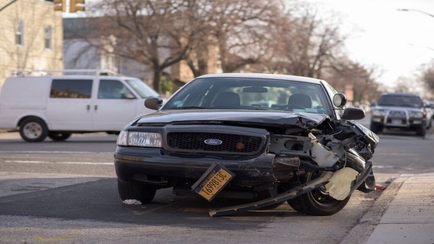
Using your car for work purposes may not be something that is protected by your standard auto insurance. If you don’t own a work vehicle, you should hire someone to drive for you and get non-owned auto liability insurance. If you operate a work vehicle on the road for your business, you will be responsible for work-related auto accident claims brought against your company after an incident happens while you or one of your workers is driving that vehicle during the day.
A strong policy is required for any company that uses cars as a part of its operations to avoid having its assets and revenue jeopardized in the aftermath of a serious accident. The majority of personal injury and auto insurance policies cover $1 million in liability and damages. Furthermore, homeowners insurance does not cover the operation of a small business; as a result, home-based business owners must consult with an agent to acquire endorsements or riders to their policy to cover their company operations.
Business Interruption Insurance
Theft, fires, floods, and building collapse are all examples of situations that could force you to temporarily close your business and lose money. The IRS expects that a company’s earnings will be back to normal after 18 months. Anything can happen in a couple of months, from losing business due to an illness or death of a major customer. If your firm is still closed after a disaster, you can get business interruption insurance to help pay for the income you lose while you are not fully operational.
Credit Insurance
If you sell items or services on credit, you expose yourself to the danger that the customer will not fulfill his/her end of the bargain. Credit insurance covers any debt losses your business may incur. Credit insurance may cover all or part of your accounts receivable and assist with your customer credit management or debt collection, depending on your policy.
Cyber Insurance
Nearly half of all companies in the United States have suffered a data breach in the last year, with 27% lacking a data breach response strategy or team. Cyber insurance is essential for every business owner to protect sensitive employee, client, and financial data in the event of a data breach.
A website is just as essential to a small firm as it is for a major corporation. But websites are vulnerable, and they must be protected. Small companies are targeted because they are less secure in the network realm. It’s simpler to get in and obtain the facts. You’re receiving the finest coverage for a cyber incident, which is valuable alone.
Employment Practices Liability Insurance
What if an employee files a lawsuit against your company? Employers are obligated by law to have certain kinds of coverage to protect their staff, but what about protection for your business if one of your employees takes action? Due to the tight-knit culture of many small companies, many owners think their personnel won’t sue, but this may not be the case. Employee practices liability insurance (EPLI) protects your business from bankruptcy if an employee brings a lawsuit.
Professional Liability Insurance
Litigation can and does occur when commercial issues must be resolved, which is what has happened to small company owners. If a client or customer files a lawsuit against your firm, professional liability insurance protects you and your brand. This is particularly significant for service-based firms and addresses some of the coverage gaps. Such insurance is required in certain businesses, such as medicine. Although, any business owner should absolutely consider it.
Professional liability insurance covers you when you are subject to a negligence lawsuit. Even if you haven’t done anything wrong, defending against a lawsuit may be costly for a small business, and insurance covers both legal representation and the settlement of any judgment awarded against you. Under 50% of small businesses don’t carry professional liability insurance.
Product Recall Insurance
As a company owner, you have an obligation to the people who buy your items. Strict liability is a legal principle that seeks to hold businesses liable for their actions. A vendor, distributor, manufacturer, or other party involved in the sale of a product that causes injury or sickness when used correctly may be held liable and responsible for those losses under this definition.
If you’re selling a product, be sure to understand the terms of your coverage and how it’s affected. No matter what type of liability insurance you have, if you need to conduct a recall due to an issue with your product or service, then it is no longer covered by that policy. To assist you with this, product recall insurance may be a valuable rider to your general liability policy. Product recall insurance can assist with the cost of recalling items, such as getting them off the shelves, breaking them down, and running a public relations or advertising campaign to restore trust in your company.
Inland Marine Insurance
When goods, materials, or equipment are transported overland – for example, by truck or train – or while temporarily stored by a third party, inland marine insurance protects them. Collisions and theft are the most prevalent claims for lost cargo under inland marine insurance coverage. For most firms, your BOP or commercial package policy (CPP) will be adequate. If you transport high-value items such as computers, construction equipment, or medical equipment overland frequently, inland marine insurance is a good idea.
Disaster Insurance
If you reside in a high-risk area for floods, tornadoes, earthquakes, or other disaster-related events, you should get insurance coverage. The premiums for disaster coverage may seem high, but you will always be covered for damages from nature that have the potential to end your business practice. Rather than depending on a physical place to avoid losing records, you should store videos of your office area, financial documents, and other crucial stuff in the cloud. This footage can be used as documentation for the claims process to ensure an adequate payout.
Key Person Insurance
If a key employee with significant responsibilities requires an absence or is lost, the company can experience more than just turbulence. That’s why several co-founders take out a key person insurance policy so that their company can continue operation. Should something happen to them, a company purchases a life insurance policy on its main employee(s) and pays the premiums for that coverage, using key person insurance. If a company’s key individual dies, the firm will get the insurance payment to keep it afloat following the death or to cover expenses associated with shutting it down.
Business Overhead Expense Insurance
Business overhead insurance is similar to key person insurance in that it protects the business owner, who is a crucial element of your company. In small firms where the owner is often engaged for the majority of the day, a lengthy absence may have a devastating influence on financial health. Business overhead compensation insurance is a form of business disability insurance that protects against the loss of earnings due to illness or accident.
What Insurance Policies Does Your Business Need?
Depending on the industry, each business has varying insurance requirements. While the aforementioned regulations are advised, they may or may not be suitable for your company. It’s important to keep contact information for your insurance agent up-to-date at all times. To ensure that your company is receiving the coverage it requires, communicate with your insurance agent on a regular basis. You should develop a regular time to meet with and update them on your company and any modifications to assure you’re receiving the coverage you require. Lastly, always remember to make sure you’re covered in every area discussed in this post.