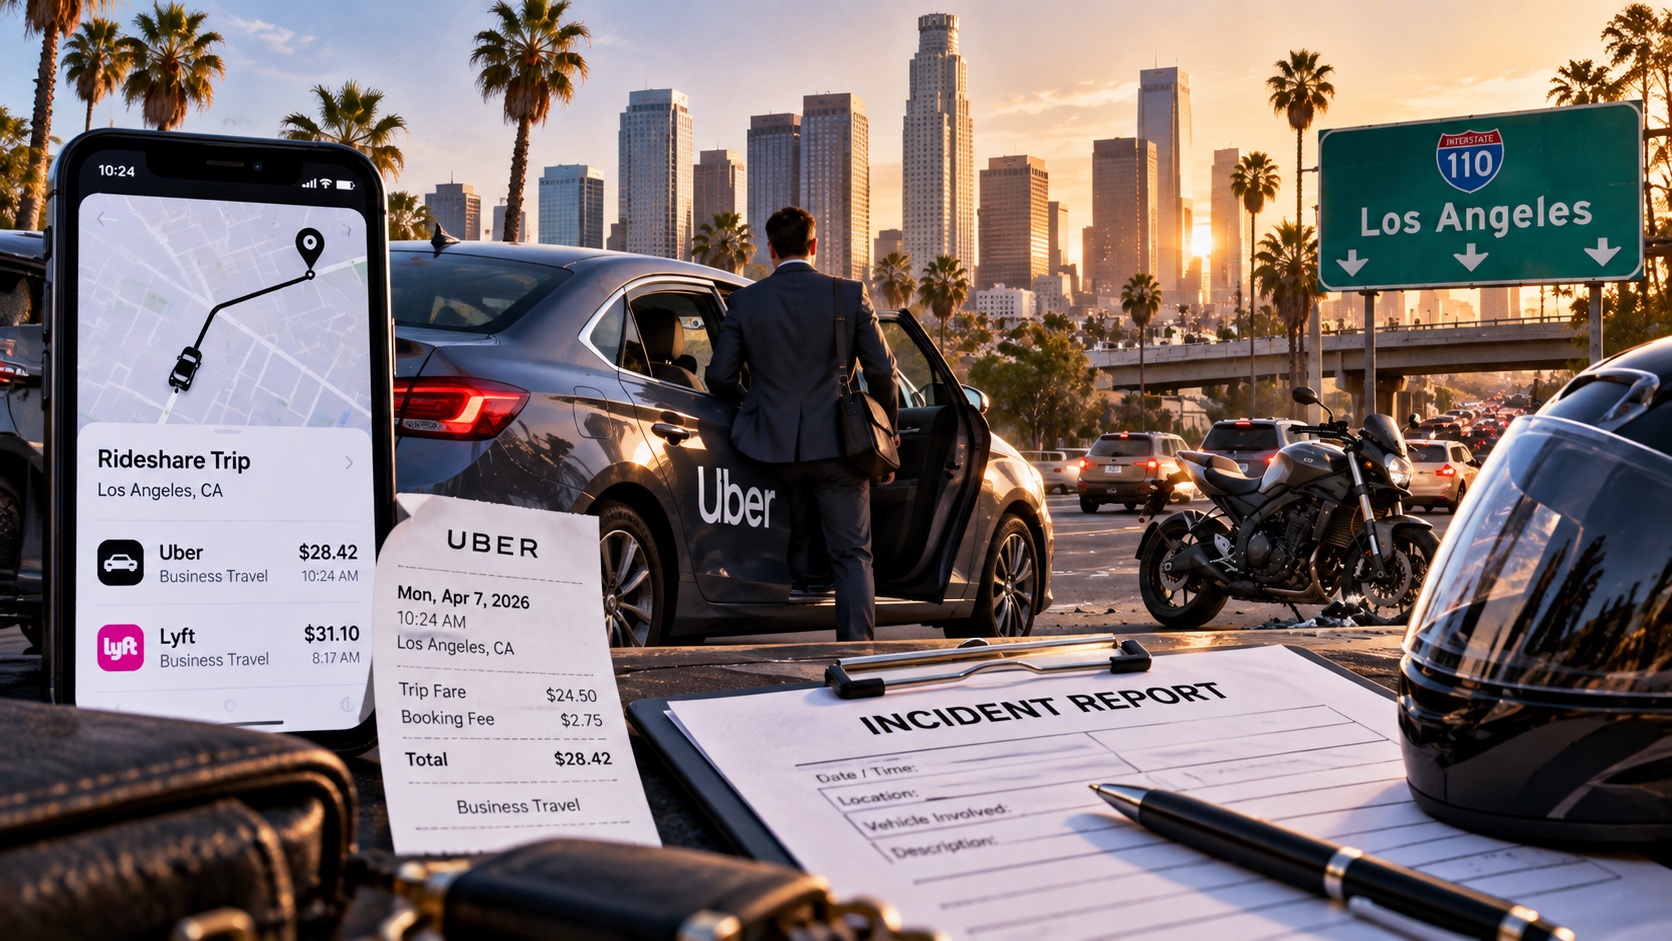

A Los Angeles business can arrange a staff journey without ever owning the vehicle involved. Who authorises the journey? Which insurance arrangements may apply? What information will the organisation still have if a serious collision occurs? For executives, the challenge is not to turn every trip into a legal exercise. It is to recognise that mobility is now distributed across personal vehicles, digital platforms and external providers. The organisation may control the business purpose and reimbursement process without controlling the driver or vehicle. Good policy acknowledges that distinction and prepares teams to respond when business travel is interrupted by injury.
An Expense Approval Is Not an Insurance Assessment
Corporate travel programs often focus on allowable fares, receipt submission and spending limits. The underlying employment and insurance arrangements must be considered separately. California Labor Code Section 2802 generally requires employers to reimburse employees for necessary expenditures or losses incurred directly in performing their duties. In a travel context, businesses should establish lawful, understandable reimbursement arrangements while separately reviewing which modes of transport are authorised. An employee’s ordinary commute, required travel between assignments and a journey chosen for personal convenience can raise different questions. HR, finance and insurance advisers should avoid treating a single expense category as a complete answer to all of them.
Why a Rideshare’s App Status Matters After a Collision
California law distinguishes periods of rideshare activity rather than applying one identical insurance requirement from the beginning to the end of a driver’s working day. Under Public Utilities Code Section 5433, when a participating driver is logged into the platform but waiting for a request, the required primary liability protection is generally at least $50,000 per injured person, $100,000 per incident and $30,000 for property damage, alongside specified excess liability coverage. Different requirements apply once a trip has been accepted.
From acceptance of a ride request through completion of the relevant transaction or trip, the law generally requires $1 million in primary transportation network company liability insurance.
A 2026 Change That Corporate Travel Policies Should Not Miss
California amended Section 5433 effective January 1, 2026. For qualifying trips, the required uninsured and underinsured motorist coverage protecting passengers from the moment they enter until they exit the vehicle is now $60,000 per person and $300,000 per incident. The previous statutory requirement was $1 million. Crucially, the change to passenger UM/UIM requirements did not eliminate the separate $1 million primary liability requirement once a driver accepts a ride. A business should not promise injured travelers that the platform will necessarily pay their expenses simply because a journey was booked through a corporate account.
Motorcycle Journeys Need Their Own Policy Logic
Motorcycles offer practical mobility in congested parts of Los Angeles, but their safety and insurance considerations differ from passenger cars. California Vehicle Code Section 21658.1 recognises lane splitting, and the California Highway Patrol explains that the practice is lawful. Legality alone does not decide whether every maneuver was safe. A company whose employees sometimes ride motorcycles for business should decide whether such journeys are authorised, how expenses will be handled and whether the organisation’s insurance arrangements address the exposure it intends to assume.
Legal information specific to these cases, including losangelespersonalinjury.attorney/practice-areas/motorcycle-accidents, illustrates why motorcycle collisions should not be evaluated using assumptions drawn exclusively from car accidents.
Build an Incident Record from Information the Business Actually Holds
The first question after a collision is always whether people need emergency assistance. A booked itinerary, expense approval or meeting schedule can help establish why an employee was traveling and which vendor or booking channel was used. A practical internal incident process can identify three categories of information: Trip details: booking confirmation, ride identification, departure and destination information, and available receipts.
Follow-up actions: insurer notification through appropriate channels, preservation requests where advised and arrangements for the employee’s absence or return. Not every company will hold every record, and confidential medical information deserves separate handling. If litigation is reasonably anticipated, legal counsel can advise on appropriate retention steps, including information that might otherwise be deleted under ordinary business processes.
Keep Employee Support Separate from Determining Fault
A serious travel-related injury may disrupt an employee’s work even when the business itself had no role in causing the accident. California generally applies comparative fault principles in negligence cases, meaning responsibility can depend on the conduct of more than one party. Code of Civil Procedure Section 335.1 generally provides two years for a personal injury action, while claims against California public entities may require much earlier administrative presentation under the Government Claims Act.
For employees and businesses trying to understand the range of potential claims after a Los Angeles collision, firms such as Cohen & Marzban Law Corporation may address the injured individual’s legal questions. Corporate leadership should obtain its own advice where employment, contractual or insurance obligations require interpretation; the employee’s interests and the organisation’s responsibilities are not necessarily identical.
The Policy Test Is What Happens on an Ordinary Tuesday
A travel policy should work for a routine customer visit, not only for a major emergency. None of these steps requires an elaborate corporate bureaucracy. The stronger approach is to review mobility arrangements when travel practices change: when a company introduces centralised rideshare bookings, expands its service territory or allows staff to use different vehicles for work. California’s updated rideshare insurance rules show why those reviews should not rely on outdated assumptions.
For Los Angeles business leaders, the essential discipline is to separate what the company can control from what requires outside verification—and to keep accurate information available when an ordinary journey becomes an unexpected incident.